Winston-Salem Home Insurance: Why Market Value Isn't Enough
In a fluctuating real estate market like the Piedmont Triad, many homeowners are dangerously underinsured because they confuse what they could sell their home for with what it costs to rebuild.
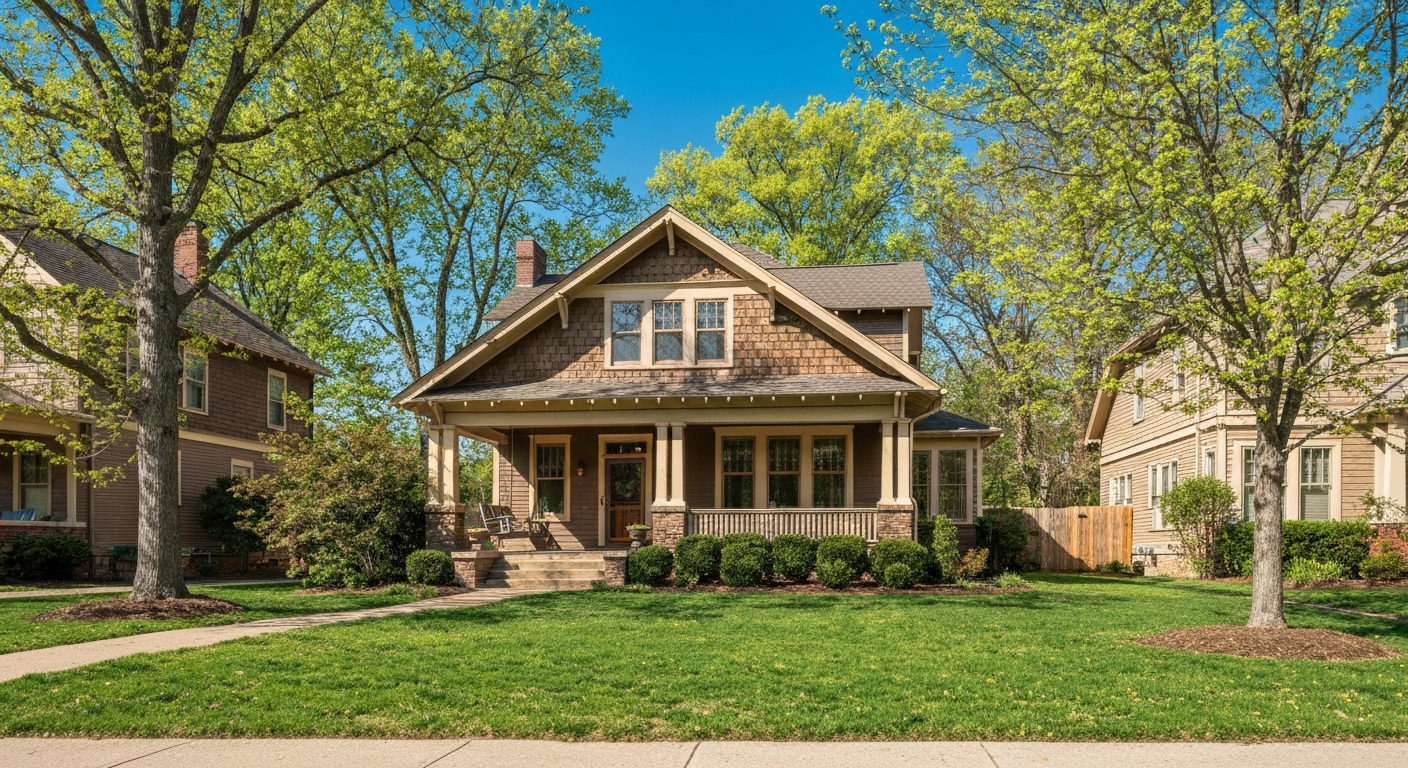
If you live in a historic neighborhood like Ardmore, West End, or Buena Vista, you know that Winston-Salem homes have character that modern construction often can't replicate. However, that character comes with a hidden risk: the cost to rebuild those unique features after a disaster can far exceed the current market value of the property.
Market Value
What a buyer is willing to pay for your home and land in today's market. This is influenced by location, school districts, and local demand.
Replacement Cost
The actual cost to rebuild your home from scratch, including labor, materials, and debris removal. This is what your insurance policy should be based on.
The "Market Value Trap" in Winston-Salem
Winston-Salem's real estate market has seen significant growth, but construction costs have risen even faster. If your home insurance policy is based on what you paid for the house five years ago, you are likely underinsured.
Consider the specialized craftsmanship found in older Winston-Salem homes:
- Plaster walls vs. modern drywall
- Solid hardwood flooring vs. engineered materials
- Custom millwork and crown molding
- Slate or tile roofing vs. asphalt shingles
Replacing these items today requires specialized labor that is in high demand across the Triad, driving up the "Replacement Cost" significantly higher than the "Market Value" in some cases.
3 Signs You Are Underinsured
You Haven't Updated Your Policy in 3+ Years
Construction material costs (lumber, copper, steel) have fluctuated wildly. An old limit is a dangerous limit.
You've Completed Renovations
That new kitchen or finished basement adds value, but it also adds to the cost of rebuilding. If you didn't tell your agent, it might not be fully covered.
Your Policy Doesn't Include "Extended Replacement Cost"
This endorsement provides a "buffer" (often 25-50%) above your policy limit to account for sudden surges in local construction costs after a widespread disaster.
How TrueGuard Helps You Get the Right Limit
As a local independent agency, we don't just guess at your home's value. We use advanced replacement cost estimators that factor in local Winston-Salem labor rates and material costs. We look at the specific details of your home to ensure that if the worst happens, you can truly rebuild. For a deeper look at how high-value properties are protected, see our guide on insuring high-value homes in Bermuda Run & Clemmons, or review our home insurance coverage options.
Is Your Home Fully Protected?
Don't wait for a claim to find out you're underinsured. Let us perform a professional replacement cost analysis for your Winston-Salem property today.
Frequently Asked Questions
What if my market value is higher than the replacement cost?
This is common in high-demand neighborhoods. You should still insure for the replacement cost. You don't need to insure the value of the land, as the land will still be there after a fire or storm.
Does my deductible affect my replacement cost?
No. The deductible is what you pay out of pocket before insurance kicks in. The replacement cost is the total limit the insurance company will pay for the structure.
What is extended replacement cost coverage?
Extended replacement cost is an endorsement that provides a buffer of 25-50% above your policy limit to account for sudden surges in local construction costs after a widespread disaster. This is especially valuable in Winston-Salem where a single storm can spike labor and material demand across the Triad.

Matt Nelson
Founder, TrueGuard Insurance. Licensed professional specializing in commercial trucking, construction equipment, and dealer programs across multiple states.