Why Standard Insurance Fails High-Value Homes in Bermuda Run & Clemmons
If your home's replacement cost exceeds $750,000, a standard homeowners policy could leave you dangerously underinsured. Here is how specialized coverage protects luxury properties.
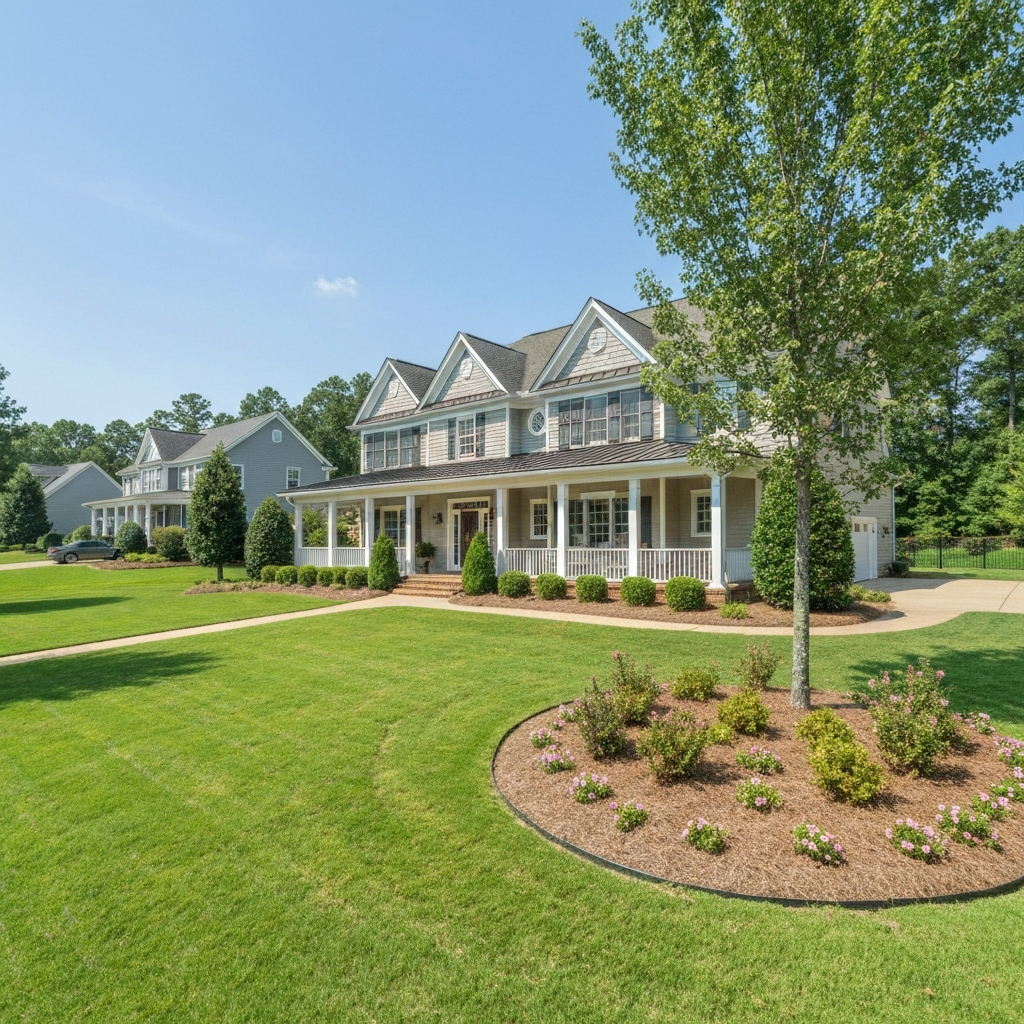
The communities of Bermuda Run and Clemmons boast some of the most beautiful and valuable real estate in the Piedmont Triad. From custom-built estates on golf courses to sprawling historic properties, these homes require a different caliber of protection.
The High-Value Home Insurance Difference
Standard homeowners insurance (HO-3) is designed for the mass market. It uses standardized formulas and limits that work perfectly well for a typical suburban home. But when applied to a custom home with high-end finishes, those limits quickly fall short.
A High-Value Homeowners Policy is specifically crafted for properties with a replacement cost typically starting around $750,000 to $1 million. These policies offer broader coverage, higher limits, and unique features that standard policies simply cannot provide.
Key Features of High-Value Policies
- Guaranteed Replacement CostIf a total loss occurs, the carrier pays whatever it takes to rebuild your home to its exact original specifications, even if it exceeds your policy limit. This is crucial given fluctuating construction costs. See our guide on replacement cost vs. market value.
- Cash Settlement OptionsIf your home is destroyed and you decide you don't want to rebuild on the same lot, high-value policies often allow you to take a cash settlement up to your policy limit.
- Coverage for High-End FinishesStandard policies often cap payouts for things like custom cabinetry, imported stone, or specialized roofing. High-value policies ensure these premium materials are fully covered.
Protecting Your Possessions
High-value homes often contain high-value contents. Standard policies place strict sub-limits on jewelry, fine art, wine collections, and antiques (often capping jewelry at just $1,500 for theft).
High-value carriers offer much higher built-in limits for these items and provide seamless options to schedule specific high-value pieces with "blanket" or "itemized" coverage, often without requiring a deductible if a loss occurs. For a broader look at scheduling collectibles, see our valuable items insurance page.
Enhanced Liability Protection
As your assets grow, so does your liability exposure. High-value home policies typically offer higher base liability limits, and they pair perfectly with high-limit Personal Umbrella policies to protect your wealth from lawsuits. They also often include coverage for unique exposures like domestic employment practices liability (if you employ a nanny, housekeeper, or landscaper).
The TrueGuard Approach
At TrueGuard Insurance, we work with premier carriers that specialize in the high-net-worth market. We understand that insuring a luxury home in Bermuda Run or Clemmons isn't just about finding coverage—it's about finding the right coverage that matches your lifestyle and protects your wealth.
Frequently Asked Questions
What is a high-value home insurance policy?
A high-value homeowners policy is designed for properties with a replacement cost typically starting around $750,000 to $1 million. These policies offer guaranteed replacement cost, higher sub-limits for luxury finishes and valuables, cash settlement options, and broader coverage than a standard HO-3 policy.
How much home insurance do I need for a luxury home in Bermuda Run or Clemmons?
Your dwelling limit should reflect the full cost to rebuild your home at today's construction prices, not its market value. For custom estates with high-end finishes, a guaranteed replacement cost policy ensures the carrier pays whatever it takes to rebuild, even if costs exceed your policy limit.
Does standard home insurance cover jewelry and fine art?
Standard policies place strict sub-limits on jewelry, fine art, and collectibles — often capping jewelry theft at just $1,500. High-value policies offer much higher built-in limits and allow you to schedule specific pieces with blanket or itemized coverage, often with no deductible.
Review Your Home's Coverage
Don't wait for a claim to find out your policy limits are too low. Contact TrueGuard Insurance for a confidential review of your high-value property insurance.