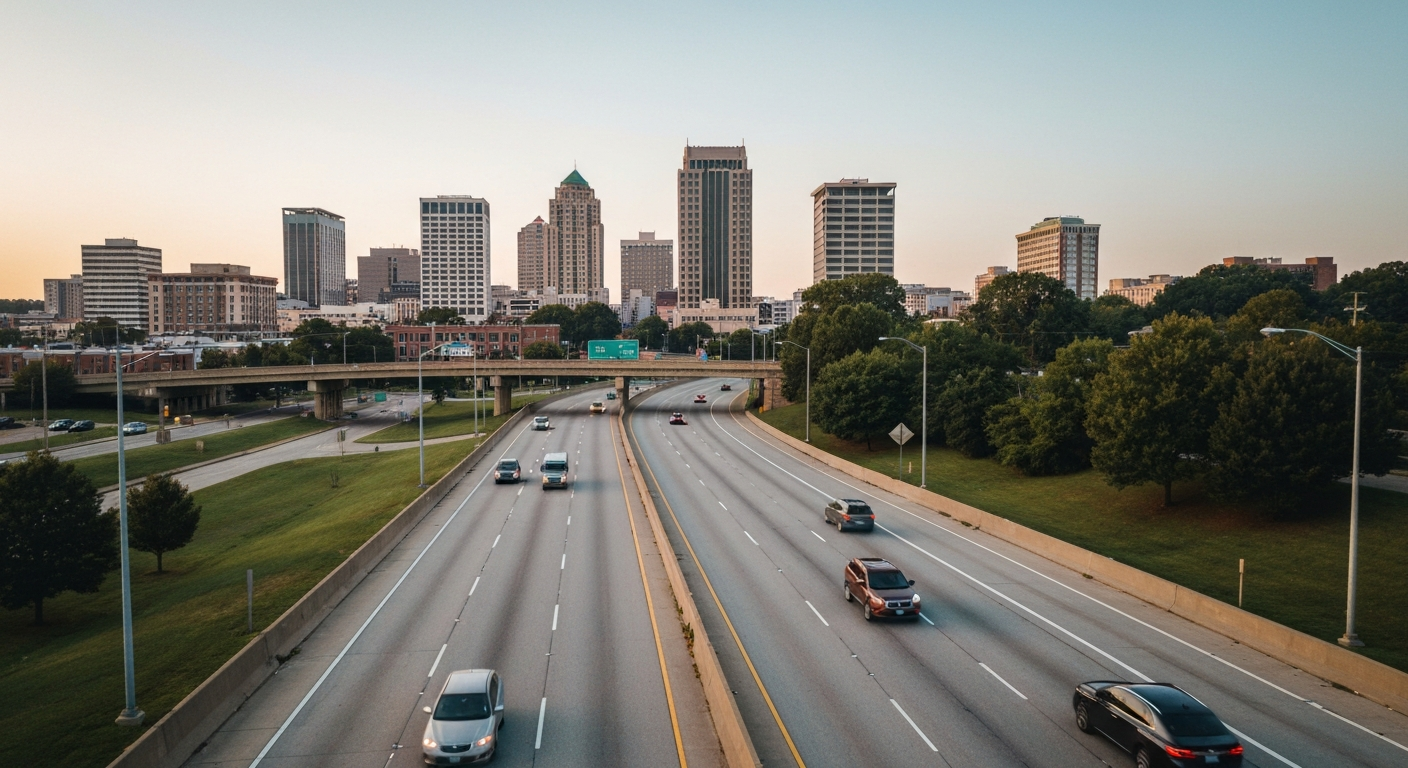
Auto Insurance for Winston-Salem Commuters: I-40, Silas Creek & Local Traffic Risks
Table of Contents
- The State Minimum is Rarely Enough
- Crucial Coverages for Local Commuters
- Local Traffic Risks on Winston-Salem's Busiest Roads
- How Commuting Distance Affects Your Auto Insurance Rate
- Deer Collisions and Wildlife Risks for Forsyth County Drivers
- Weather-Related Driving Risks in the Piedmont Triad
- How to Keep Your Rates Low
- Why a Local Independent Agent Saves You More
Whether you are commuting to Wake Forest Baptist Medical Center, heading downtown via Salem Parkway, or navigating the heavy commercial traffic on I-40, driving in Winston-Salem requires keen attention—and the right auto insurance coverage.
As the Piedmont Triad continues to grow, traffic density has increased significantly across Winston-Salem. With more drivers on the road, the statistical risk of fender benders on Silas Creek Parkway or more serious collisions on the interstate goes up. Understanding how local roads, weather, and wildlife affect your risk profile helps you choose the right coverage before you need it.
This guide is written specifically for Winston-Salem commuters who drive I-40, Silas Creek Parkway, Salem Parkway, University Parkway, and Peters Creek Parkway on a daily or weekly basis. If you want a broader overview of coverage types, start with our complete guide to understanding auto insurance coverage before diving into the local specifics here.
The State Minimum is Rarely Enough
North Carolina requires a minimum liability limit of 30/60/25 ($30,000 per person / $60,000 per accident / $25,000 property damage). If you cause a multi-car pileup on I-40, $25,000 won't even cover the replacement cost of one new SUV, leaving your personal assets exposed to lawsuits. For most Winston-Salem commuters, 100/300/100 liability limits are a more appropriate starting point.
Crucial Coverages for Local Commuters
Beyond the state minimum, every Winston-Salem commuter should understand these six coverage types that protect against the specific risks of daily Triad driving.
1. Uninsured & Underinsured Motorist (UM/UIM)
Despite state laws requiring insurance, an estimated 7 to 10 percent of drivers on North Carolina roads are driving without coverage. If an uninsured driver hits you at the Peters Creek Parkway intersection, UM coverage pays for your medical bills and vehicle damage. Underinsured Motorist (UIM) coverage kicks in when the at-fault driver has state minimums that are not high enough to cover your total costs after a serious collision on I-40.
North Carolina requires UM coverage at the same limits as your liability policy, but you can request higher limits for additional protection. Given the uninsured driver rate in the Triad, TrueGuard recommends carrying at least 100/300 in UM limits.
2. Comprehensive Coverage
Comprehensive coverage is your Piedmont weather protection. Winston-Salem is prone to severe thunderstorms, hail, and falling tree branches, particularly during spring and summer months. Comprehensive coverage pays for damage to your vehicle from these non-collision events as well as theft, vandalism, fire, and animal collisions.
If your car is parked outside during a hailstorm in Forsyth County — which happens multiple times per year — comprehensive coverage pays for the dents and glass damage. Without it, you are paying out of pocket for repairs that can easily exceed several thousand dollars.
3. Collision Coverage
Collision coverage pays for damage to your vehicle resulting from a collision with another vehicle or object, regardless of who is at fault. On busy Winston-Salem roads like I-40, Silas Creek Parkway, and University Parkway, even a minor fender bender can cause thousands of dollars in damage to modern vehicles with complex sensors and cameras.
If you are financing or leasing your vehicle, your lender almost certainly requires collision and comprehensive coverage. But even if you own your car outright, collision coverage is worth considering if your vehicle's value exceeds what you could comfortably pay to replace.
4. Rental Reimbursement
If your car is in the body shop after a wreck on Stratford Road, how will you get to work? Rental reimbursement coverage pays the daily cost of a rental car while your vehicle is being repaired after a covered claim. Given that auto part shortages are still causing extended repair timelines across the Triad, this coverage is more valuable than ever.
Most carriers offer rental reimbursement limits ranging from $20 to $50 per day, with maximum limits of 30 days or more. A TrueGuard agent can help you choose the right daily limit based on what rental cars actually cost in the Winston-Salem area.
5. Medical Payments (MedPay)
Medical Payments coverage, also known as MedPay, covers medical expenses for you and your passengers regardless of who caused the accident. It pays for deductibles, copays, and other out-of-pocket medical costs that your health insurance may not cover after a crash.
MedPay is an affordable add-on — typically $5 to $15 per month for $5,000 in coverage — and TrueGuard strongly recommends it for all Winston-Salem drivers. If you are ever in an accident, read our step-by-step guide on what to do after a car accident to understand how MedPay and your other coverages work together.
6. Roadside Assistance
A flat tire on I-40 during rush hour or a dead battery in a parking deck downtown can leave you stranded. Roadside assistance covers towing, tire changes, fuel delivery, jump starts, and lockout service. For commuters who depend on their vehicle to get to work every day, this coverage is a practical necessity.
Most carriers offer roadside assistance as a low-cost add-on to your comprehensive coverage, typically $5 to $15 per month. It can also be bundled with rental reimbursement for a more complete protection package.
Local Traffic Risks on Winston-Salem's Busiest Roads
Every Winston-Salem commuter knows that certain roads carry more risk than others. Here is a breakdown of the highest-traffic corridors in Forsyth County and the insurance considerations for each.
I-40: The Triad's Main Artery
I-40 carries the highest volume of traffic in the Winston-Salem area, connecting the city to Greensboro, High Point, and the rest of the state. Heavy truck traffic, high speeds, and frequent congestion during rush hours create a high accident environment. Multi-vehicle pileups are not uncommon, particularly during inclement weather. Higher liability limits and strong UM/UIM coverage are essential for daily I-40 commuters.
Silas Creek Parkway
Silas Creek Parkway connects residential areas to Wake Forest University, Baptist Medical Center, and major shopping centers. Its winding curves, frequent traffic lights, and high volume of turning vehicles create numerous side-impact collision risks. Collision coverage is particularly important for drivers who use this route daily.
Salem Parkway (Business 40)
The newly renovated Salem Parkway (formerly Business 40) runs through downtown Winston-Salem and carries a mix of commuter and commercial traffic. The tighter lanes and reduced speeds compared to I-40 create a different risk profile — more low-speed collisions but fewer high-speed crashes. Comprehensive coverage protects against the downtown theft and vandalism risks that are higher in urban corridors.
University Parkway and Peters Creek Parkway
These two major north-south arteries carry heavy commuter traffic and connect to some of the busiest intersections in the city. Rear-end collisions are the most common claim type at traffic lights along these routes. Rental reimbursement coverage is a smart add-on if you regularly drive these corridors, since even minor repairs can keep your car in the shop for several days.
How Commuting Distance Affects Your Auto Insurance Rate
Insurance carriers calculate your premium partly based on your estimated annual mileage, which is directly influenced by your daily commute. If you drive from Clemmons to downtown Winston-Salem every day — roughly 20 miles each way — you are putting significantly more miles on your vehicle than someone who works from home.
Short Commute (Under 10 Miles)
Drivers with short commutes generally see the lowest rates, as less time on the road means fewer accident opportunities. If you work from home or have a very short commute, ask your agent about a low-mileage discount.
Long Commute (Over 20 Miles)
Long-distance commuters pay more due to increased annual mileage and highway exposure. However, highway driving is sometimes rated lower than city driving per mile, as highway accidents tend to be less frequent even if more severe.
Be accurate when reporting your commute distance to your insurance agent. Misrepresenting your annual mileage can result in a denied claim if the carrier discovers the discrepancy during an investigation. For more strategies on reducing your premium, read our guide on how to lower your auto insurance rates in North Carolina.
Deer Collisions and Wildlife Risks for Forsyth County Drivers
Forsyth County and the surrounding rural areas of Davie, Yadkin, and Stokes counties have dense deer populations. Deer collisions are one of the most common comprehensive claims in the region, particularly during the fall mating season from October through December and again in late spring.
Peak Deer Activity Hours
Deer are most active at dawn and dusk — exactly when many Winston-Salem commuters are on the road. The stretches of I-40 between Winston-Salem and Clemmons, Highway 67 through Davie County, and rural sections of US-421 are particularly high-risk corridors for deer strikes.
Comprehensive coverage — not collision — pays for deer strike damage. If you hit a deer on your commute home from work, your comprehensive deductible applies. Without comprehensive coverage, you are paying for vehicle repairs out of pocket, and a single deer collision can cause thousands of dollars in damage to the front end of a modern vehicle.
The average deer collision claim in North Carolina exceeds $4,000 in vehicle damage, and that does not include medical costs if injuries occur. For commuters who regularly drive rural routes at dawn or dusk, comprehensive coverage is not optional — it is essential financial protection.
Weather-Related Driving Risks in the Piedmont Triad
The Piedmont Triad's climate creates several weather-related risks that directly affect auto insurance claims and premiums.
Severe Thunderstorms and Hail
Spring and summer in the Triad bring severe thunderstorms with high winds, large hail, and flash flooding. Hail damage to vehicles is one of the most common comprehensive claims in Forsyth County, with repairs often exceeding $3,000 for body panels, windshields, and roof damage. Comprehensive coverage pays for all storm-related vehicle damage.
Ice Storms and Winter Weather
While Winston-Salem does not see heavy snowfall regularly, ice storms are a significant winter risk. Black ice on bridges and overpasses causes numerous single-vehicle accidents each winter, and collision coverage pays for damage from ice-related crashes. Even a low-speed slide on ice into a guardrail can cause thousands in damage.
Falling Trees and Limbs
Many Winston-Salem neighborhoods are heavily wooded, and severe storms regularly bring down tree limbs and entire trees onto parked vehicles. Comprehensive coverage pays for damage from falling objects, and your deductible applies. If a neighbor's tree falls on your car, your comprehensive coverage still covers the damage.
How to Keep Your Rates Low
Auto insurance rates are rising nationwide, but working with a local independent agency like TrueGuard gives you an advantage. Because we are not tied to one carrier, we can shop your policy across multiple A-rated companies to find the best rate for your specific commuting profile.
- Bundle Your Policies: Combining your auto and home or renters insurance can save you up to 20 percent on both policies.
- Telematics Programs: If you are a safe driver, opting into a carrier's tracking app can yield discounts of up to 30 percent based on your actual driving habits.
- Review Your Deductibles: Raising your deductible from $500 to $1,000 can noticeably lower your monthly premium. Just make sure you can comfortably cover the higher deductible if you need to file a claim.
- Shop Multiple Carriers Annually: Insurance companies change their rating models constantly. The carrier that was cheapest three years ago may not be the best option today. TrueGuard compares rates from 25+ carriers to keep you in the most competitive program.
- Maintain Continuous Coverage: A lapse in coverage — even for a few days — can significantly increase your rates when you reinstate. Set up auto-pay or work with TrueGuard to ensure your policy never lapses.
- Improve Your Credit Score: In North Carolina, your credit-based insurance score impacts your premium. Improving your credit can move you into a better rating tier and save hundreds of dollars per year.
Why a Local Independent Agent Saves You More
When you buy auto insurance directly from a single carrier or through a national online portal, you are getting one company's price for one company's product. There is no comparison, and there is no advocate when you need help with a claim.
As an independent agency based right here in Winston-Salem, TrueGuard Insurance shops your policy across more than 25 top-rated carriers simultaneously. That means you get multiple quotes from one conversation, and we handle the comparison shopping for you. We also serve as your claims advocate — if your carrier undervalues your claim or delays a payout, we intervene on your behalf. For a broader look at what's available locally, read our complete guide to auto insurance in Winston-Salem.
Drive with Confidence on Winston-Salem Roads
Let TrueGuard Insurance build a customized auto policy that truly protects you on your daily commute through the Triad. Compare rates from 25+ top-rated carriers in minutes — no obligation, no pressure.

Matt Nelson
Founder, TrueGuard Insurance. Licensed professional specializing in commercial trucking, construction equipment, and dealer programs across multiple states.
Related Articles
Understanding Your Auto Insurance Coverage Options
A complete breakdown of every auto insurance coverage type available to North Carolina drivers.
Read Article
How to Lower Your Auto Insurance Rates in NC
Practical strategies to reduce your auto insurance premiums without sacrificing essential coverage.
Read Article
What to Do After a Car Accident in NC
Step-by-step guide for North Carolina drivers — from the moment of impact to filing your claim.
Read Article